Under UCC § 9-612, whether a disposition notice was sent within a reasonable time is generally a question of fact. For a transaction other than a consumer transaction, however, a notice sent after default at least 10 days before the earliest disposition time stated in the notice falls within a statutory safe harbor.
What Is the UCC § 9-612 10-Day Safe Harbor?
UCC § 9-612 provides an important timing benchmark for secured creditors conducting a disposition in a non-consumer transaction.
When an authenticated notification is sent after default and at least 10 days before the earliest time of disposition stated in the notice, the notification is considered to have been sent within a reasonable time.
This gives secured creditors a clear statutory safe harbor when planning a commercial collateral disposition.
Outside the safe harbor, the reasonableness of the timing may become a fact-specific question.
How Should a Secured Creditor Build the Sale Timeline?
A creditor should work backward from the earliest date on which the collateral could realistically be sold.
Step 1: Confirm Default
The secured party should first confirm the contractual and legal basis for enforcement.
Step 2: Identify Required Notice Recipients
The debtor, any secondary obligor, and other parties potentially entitled to notification under UCC § 9-611 should be identified.
Step 3: Establish the Earliest Disposition Date
For a non-consumer transaction, the creditor can then choose an earliest disposition date that preserves the 10-day safe-harbor period.
Step 4: Allow Enough Time for the Market
The creditor should not confuse the 10-day notice safe harbor with the amount of time required to conduct a commercially reasonable sale.
Specialized collateral may need substantially more time for marketing, buyer diligence, inspection, financing, or competitive bidding.
Does the 10-Day Safe Harbor Apply to Consumer Transactions?
No. The 10-day safe harbor in UCC § 9-612(b) applies to transactions other than consumer transactions.
Consumer transactions may be affected by additional Article 9 provisions as well as state consumer-protection statutes, retail installment laws, vehicle repossession laws, and other requirements.
A secured creditor should therefore not automatically use the same timeline for a consumer repossession that it would use for a commercial equipment disposition.
Example: Calculating the Earliest Sale Date
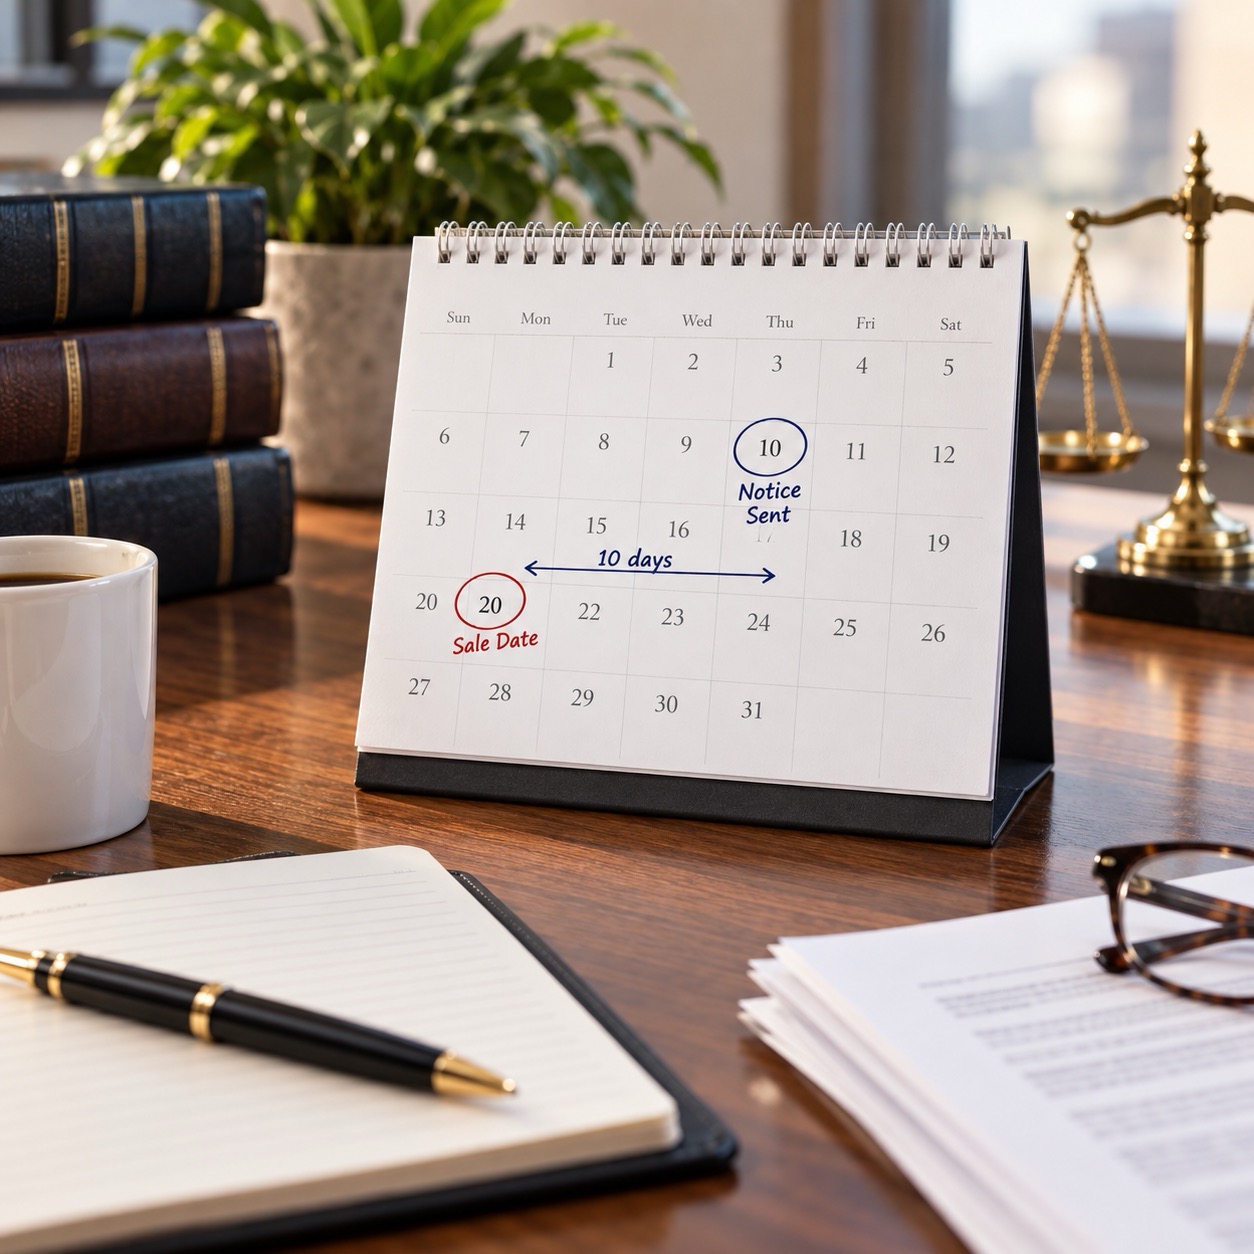
Assume a commercial borrower defaults and the secured creditor intends to conduct a private sale of business equipment.
The disposition notice states that the collateral may be sold on or after October 20.
If the notice is sent after default at least 10 days before that earliest sale date, the notice falls within the timing safe harbor provided by UCC § 9-612 for a non-consumer transaction.
That does not end the compliance analysis.
The creditor still must confirm that all required parties received notice under UCC § 9-611 and that the final disposition is commercially reasonable under UCC § 9-610.
Common UCC § 9-612 Timing Mistakes
- Treating 10 days as the required marketing period. The notice safe harbor and the amount of marketing time needed for a commercially reasonable sale are different issues.
- Sending notice before identifying all recipients. A missed secured party or secondary obligor can force the creditor to revisit the timeline.
- Scheduling the sale earlier than stated in the notice. The disposition should remain consistent with the timing communicated to recipients.
- Using the rule automatically for consumer transactions. The statutory safe harbor applies to non-consumer transactions.
- Failing to preserve evidence of sending. The secured creditor should maintain documentation showing when and how notification was sent.
Why 10 Days May Not Be Enough for the Sale Process
A creditor can comply with the UCC § 9-612 safe harbor and still have a commercially unreasonable disposition.
For example, specialized manufacturing machinery may require several weeks of targeted marketing, buyer outreach, inspections, and competitive bidding.
The notice requirement establishes one timing benchmark, but UCC § 9-610 still requires the entire disposition process to be commercially reasonable.
For more detail, review our guide to notification of disposition under UCC § 9-611 and our article explaining commercially reasonable Article 9 sales .
Frequently Asked Questions
Is 10 days always enough notice under Article 9?
For a non-consumer transaction, UCC § 9-612 provides a safe harbor when notice is sent after default at least 10 days before the earliest disposition time stated in the notice. Other Article 9 requirements still apply.
Can a notice sent less than 10 days before the sale still be reasonable?
Potentially. Outside the safe harbor, whether the notification was sent within a reasonable time generally becomes a fact-specific issue.
Does the 10-day rule apply to consumer transactions?
No. The statutory safe harbor in UCC § 9-612(b) applies to transactions other than consumer transactions.
Should a creditor ever give more than 10 days?
Yes. More time may be appropriate when collateral is complex, inspections are required, the buyer market is specialized, or additional marketing is necessary to support a commercially reasonable sale.
Does complying with § 9-612 automatically make the sale commercially reasonable?
No. Notice timing is only one part of the Article 9 process. The method, manner, timing, place, marketing, and terms of the disposition must still satisfy the commercial reasonableness requirements of UCC § 9-610.
Legal Note: Article 9 is enacted through state law, and state-specific statutes, court decisions, transaction documents, and consumer-protection rules may change the analysis. This article is for general informational purposes and is not legal advice.