UCC § 9-610 permits a secured party, after default, to sell, lease, license, or otherwise dispose of collateral. The central requirement is that every aspect of the disposition, including the method, manner, time, place, and terms, must be commercially reasonable.
What Does UCC § 9-610 Require After Default?
After a debtor defaults, Article 9 generally allows a secured party to sell, lease, license, or otherwise dispose of some or all of the collateral.
The collateral may be disposed of in its existing condition or after commercially reasonable preparation or processing.
The most important requirement is not simply whether the collateral was sold. UCC § 9-610 requires that every aspect of the disposition be commercially reasonable.
That includes the method of sale, the manner in which the collateral is marketed, the timing of the transaction, the place of sale, and the terms ultimately accepted by the secured creditor.
This means a secured creditor should be able to explain why the chosen sale process made sense for the specific asset and the market in which that asset would normally be sold.
Public Sale vs. Private Sale Under Article 9
UCC § 9-610 allows both public and private dispositions, provided that the overall process is commercially reasonable.
Public Disposition
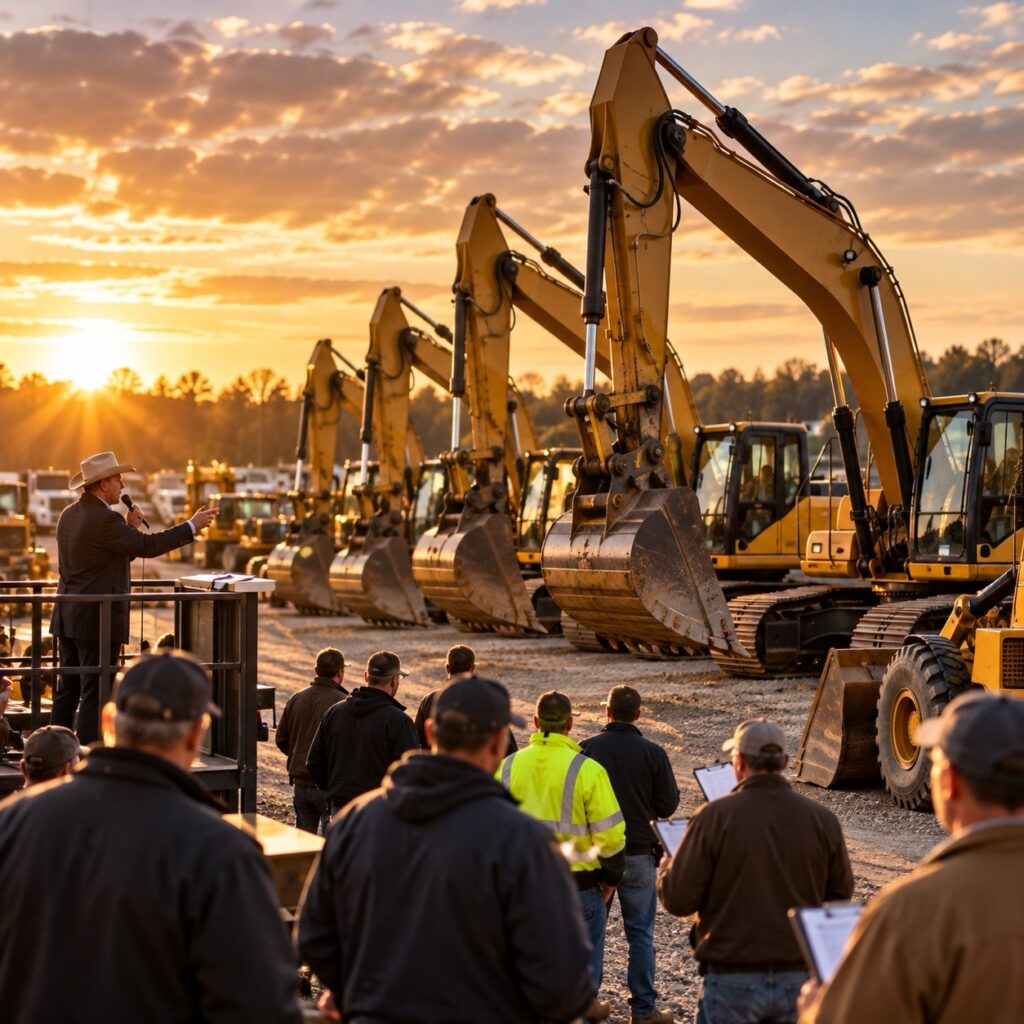
A public disposition generally exposes the collateral to competitive bidding and provides members of the relevant market with an opportunity to participate.
An auction is one common example.
A properly marketed public sale can create useful evidence of market demand because the secured creditor can document advertising, registrations, inspections, bids, and the final sale result.
Private Disposition
A private disposition usually involves a negotiated transaction with one or more identified buyers.
Private sales can be particularly appropriate for specialized assets where the realistic buyer pool is limited, but they often require strong documentation showing how buyers were identified and how the price was evaluated.
What Makes an Article 9 Sale Commercially Reasonable?
There is no single auction format, marketing period, or pricing method that automatically makes a disposition commercially reasonable.
The correct process depends on the collateral and the market for that collateral.
Important considerations can include:
- Buyer market: Where are qualified buyers for this type of asset normally found?
- Marketing: Was the opportunity presented to a meaningful number of likely buyers?
- Timing: Did potential buyers have enough time to evaluate the collateral?
- Information: Were buyers given sufficient specifications, condition information, inspection access, or other relevant diligence materials?
- Valuation: Was an appraisal, broker opinion, market comparison, or other pricing benchmark appropriate?
- Asset preparation: Would reasonable repairs, cleaning, sorting, or presentation improve the expected net recovery?
- Sale structure: Would the collateral likely produce more value when sold individually, in groups, or as one package?
A low sale price does not automatically establish that a disposition was commercially unreasonable.
However, an unusually low result combined with weak marketing, limited buyer exposure, insufficient information, or a rushed process may create significant problems if the sale is later challenged.
Example: Selling Specialized Manufacturing Equipment
Assume a lender repossesses specialized manufacturing equipment after a commercial borrower defaults.
Shortly after repossession, a local equipment dealer offers to buy all of the machinery.
Accepting the first offer may be fast, but speed alone does not necessarily demonstrate that the sale process was commercially reasonable.
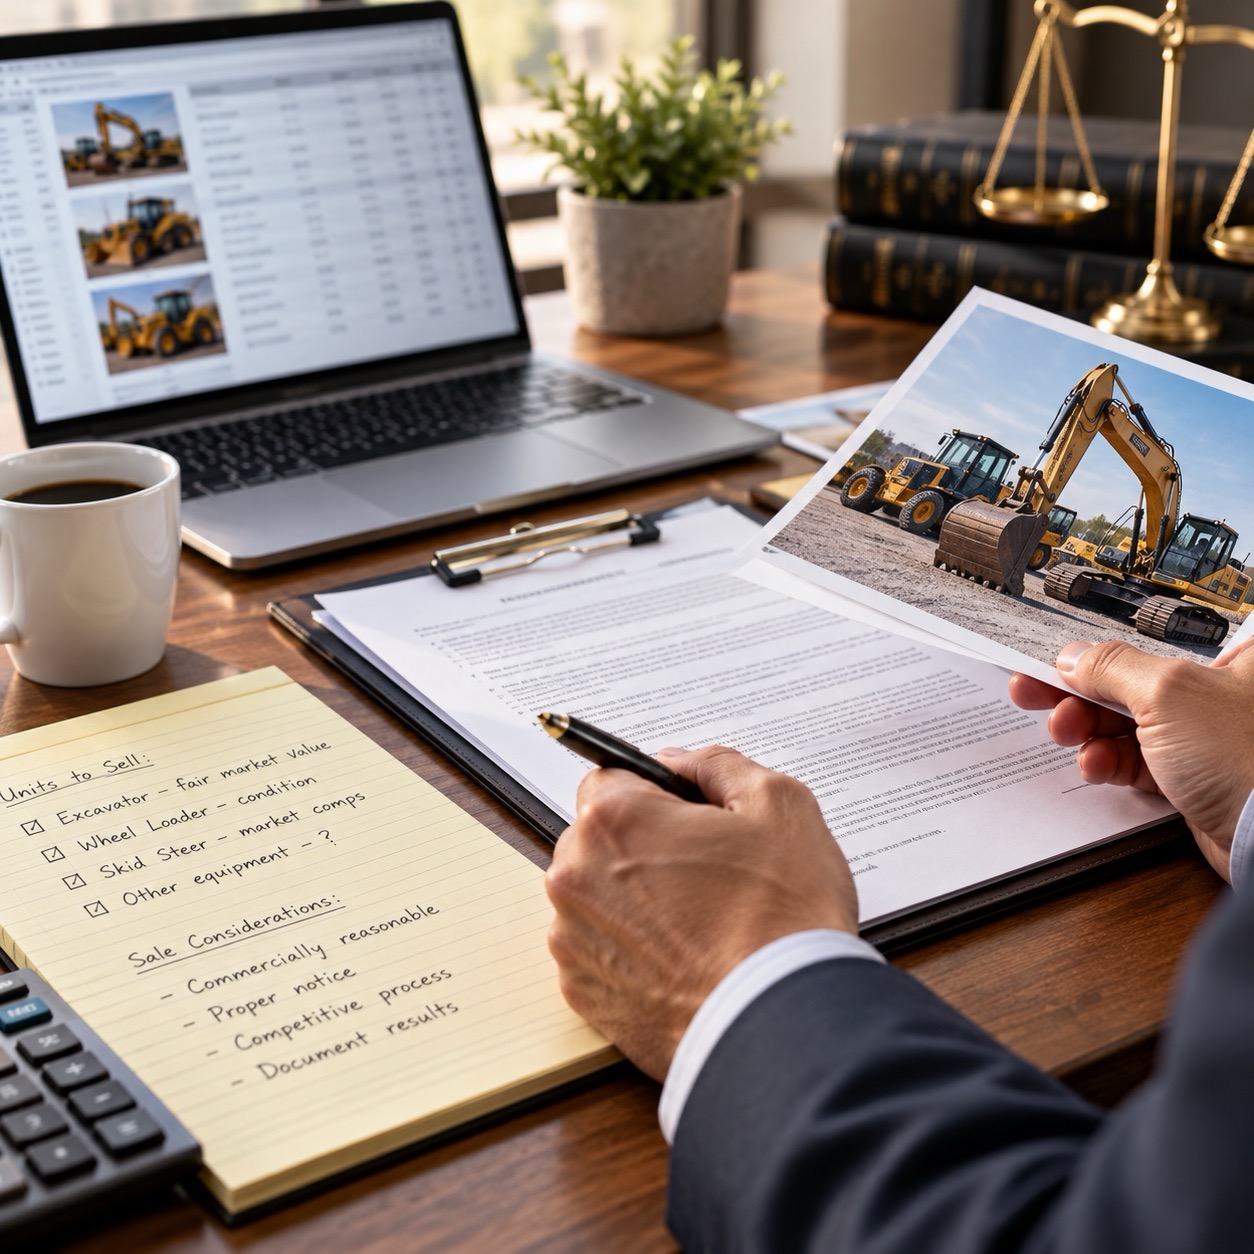
A stronger process may involve obtaining a current valuation, identifying specialized equipment dealers and industry operators, circulating specifications, allowing inspections, and requesting competitive offers.
The lender can then compare the offers received against available market information and document why the selected buyer and sale terms were reasonable.
If the original dealer still submits the strongest offer, the documented market-testing process can help demonstrate that the creditor did not simply accept an untested price.
What Should a Secured Creditor Document Before and After the Sale?
Documentation becomes particularly important when the debtor later challenges the disposition or when the creditor seeks to recover a deficiency.
A strong sale file may include:
- Collateral inventory
- Current photographs and condition reports
- Independent valuations or appraisals
- Buyer and dealer lists
- Marketing plans
- Email and direct buyer outreach
- Advertisements
- Auction listings
- Inspection records
- Buyer questions
- Offers and bids
- Auction reports
- Internal sale approval records
- Final sale agreement
- Closing documentation
The goal is to preserve enough information to reconstruct the creditor’s decision-making process if the sale is reviewed later.
UCC § 9-610 Does Not Operate Alone
A commercially reasonable sale process is only one part of Article 9 enforcement.
Before the disposition, the secured creditor may also have notification obligations under UCC § 9-611 and timing requirements under § 9-612.
After the sale, UCC § 9-615 governs how disposition proceeds are applied and how a surplus or deficiency may be calculated.
For a broader overview, read our UCC Article 9 Sales Guide for Secured Creditors .
You can also review our guide explaining what makes an Article 9 sale commercially reasonable .
Frequently Asked Questions
Does UCC § 9-610 require an auction?
No. Article 9 allows both public and private dispositions, as long as the applicable requirements are satisfied and the disposition is commercially reasonable.
Can a secured creditor sell repossessed collateral privately?
Yes. A private disposition is permitted, but the secured creditor should be able to demonstrate that the method, timing, marketing, buyer selection, and sale terms were commercially reasonable.
Can the secured creditor purchase the collateral?
A secured party may generally purchase the collateral at a public disposition. Purchases at private dispositions are more restricted under UCC § 9-610.
Does an appraisal automatically make the sale commercially reasonable?
No. An appraisal can be valuable evidence, but commercial reasonableness generally depends on the complete disposition process rather than any single valuation.
Can a secured creditor sell collateral without court approval?
Article 9 can permit a secured party to dispose of collateral after default without a judicial sale, subject to the creditor’s enforcement rights, the governing agreements, Article 9 requirements, and other applicable law.
Legal Note: Article 9 is enacted through state law, and state-specific statutes, court decisions, transaction documents, and consumer-protection rules may change the analysis. This article is for general informational purposes and is not legal advice.